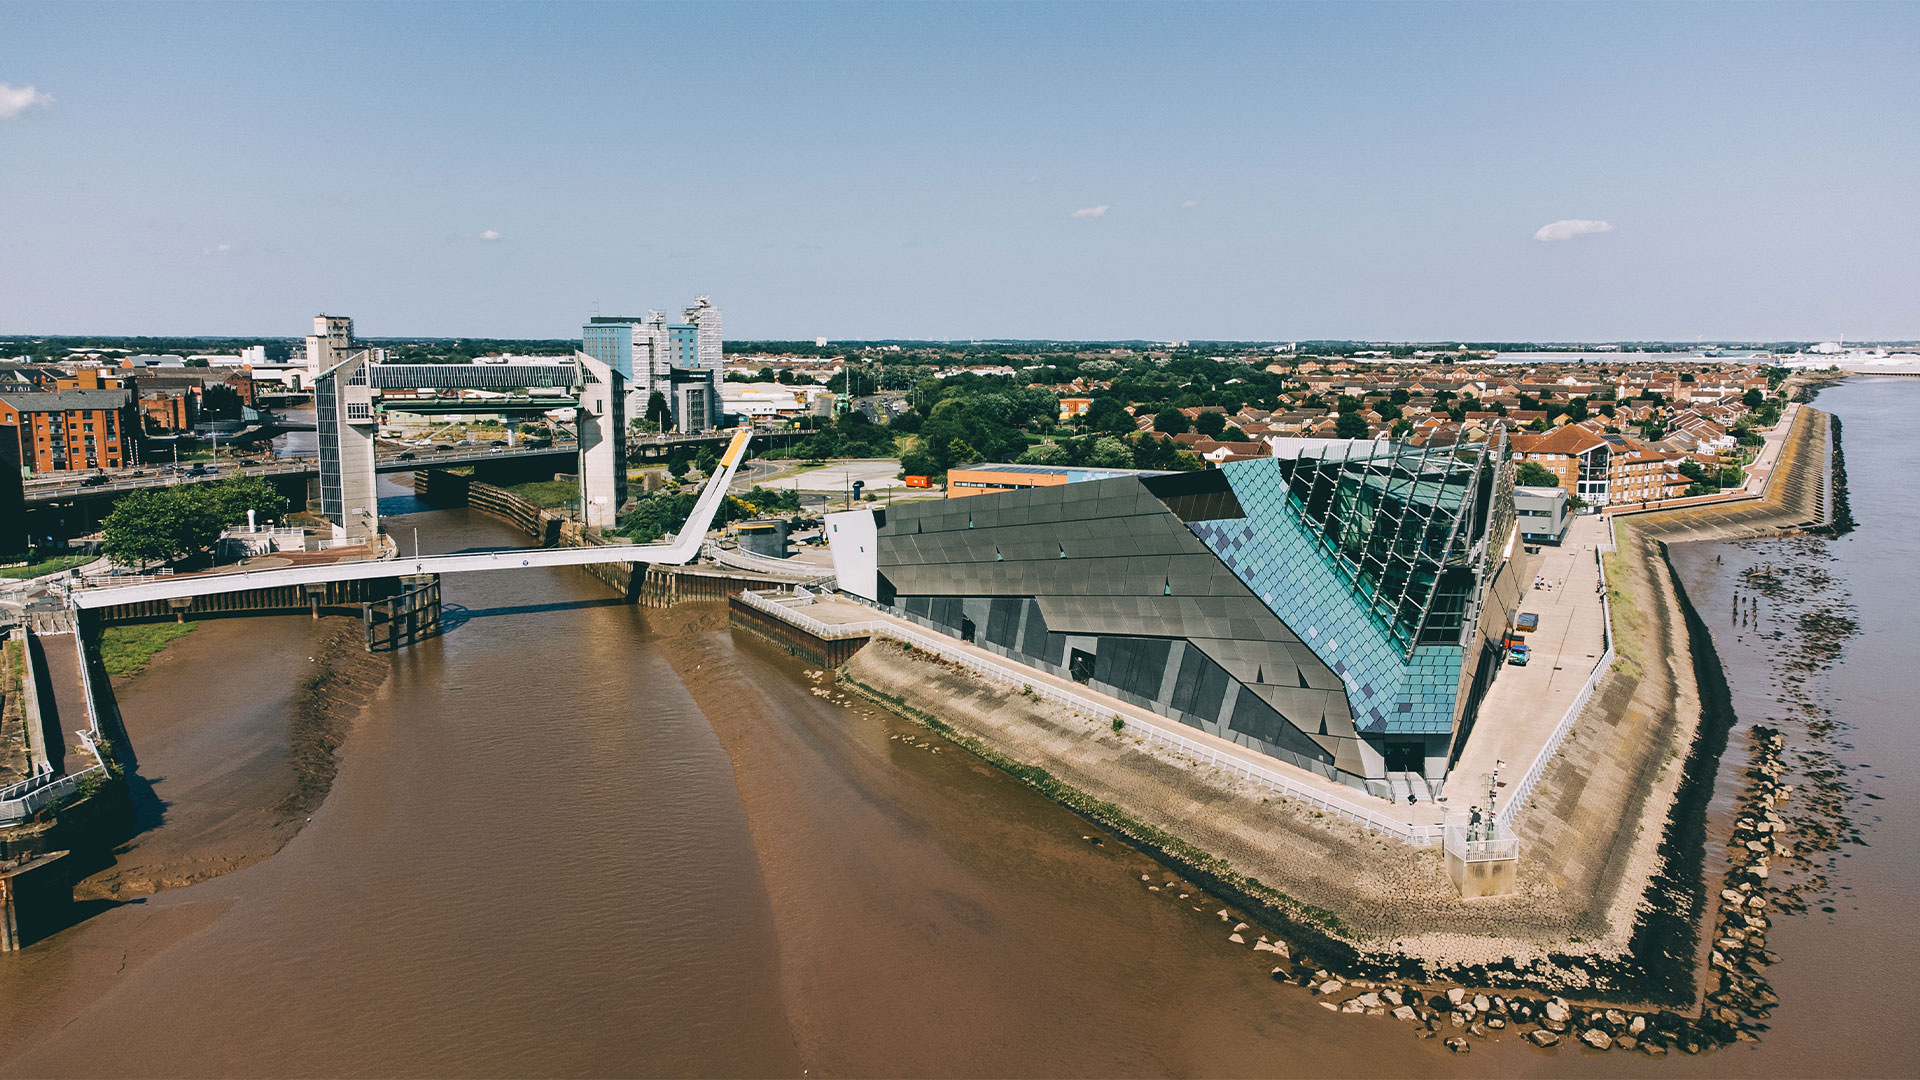

Hull has been named one of the most affordable places in Britain to buy a home, according to new research from Lloyds.
The figures, reported by Yorkshire.com, show that the average home in Kingston upon Hull costs around 3.6 times average local earnings, placing the city joint third for affordability across Britain.
That compares with 7.3 times average earnings nationally, which itself has fallen from 7.6 a year earlier and is now at its lowest level since 2015.
For anyone thinking about buying a home in Hull, this is encouraging news.
It does not necessarily mean getting a mortgage has suddenly become easier, though it does show how far your income and deposit could potentially stretch compared with other parts of the country.
Why Has Housing Affordability Improved?
The improvement nationally has largely come from earnings rising faster than house prices.
According to the Lloyds research, average UK earnings increased by 4.5% over the year, while average property prices increased by 0.5%. This has gradually narrowed the gap between what people earn and what homes cost.
There has been improvement closer to home too. Across Yorkshire and the Humber, the average house-price-to-earnings ratio has fallen from 6.0 to 5.8.
Hull stands out considerably within the region at 3.6, with the research putting the average property price in the city at £134,642.
That does not mean every property in Hull will be affordable to every buyer. Property prices vary considerably by area and property type, while mortgage affordability is assessed individually by lenders.
What Does This Mean If You Want a Mortgage in Hull?
A lower house-price-to-earnings ratio can make getting onto the property ladder more achievable, though lenders do not simply compare your salary with the average price of a home.
When you apply for a mortgage, lenders will look at your income, regular outgoings, existing credit commitments and deposit, alongside their own affordability criteria.
This means two people earning the same amount could be offered very different borrowing amounts.
As a mortgage broker in Hull, this is something we regularly see when speaking to buyers.
Knowing that the local market is comparatively affordable is useful, though understanding what you can personally borrow gives you a much clearer idea of the properties realistically within reach.
Is Hull Becoming More Affordable for First Time Buyers?
The national picture has improved for first time buyers too.
Lloyds found that a typical first time buyer property now costs 5.9 times average earnings, down from 6.1 a year ago and the lowest ratio recorded since 2015.
Hull’s comparatively low property prices could put some first time buyers locally in a stronger starting position, particularly where they have already built up a deposit.
The deposit can still be one of the biggest barriers to buying.
You may only need a 5% deposit for some mortgages, subject to lender criteria, while having more available could give you access to a wider choice of products.
Before starting your property search, getting an Agreement in Principle can also help establish what a lender may be prepared to offer.
We can typically provide an Agreement in Principle within 24 hours of your initial appointment.
Affordability Does Not Just Mean House Prices
There is an important distinction in the latest figures.
Homes may have become more affordable relative to earnings, though mortgage repayments have not necessarily become cheaper.
Lloyds found that average monthly mortgage repayments across the UK have increased over the past year as borrowing costs have risen.
For buyers in Hull, this makes the mortgage itself just as important as the purchase price.
A property might comfortably sit within your overall budget, yet the interest rate, mortgage term and size of your deposit can all make a significant difference to what you pay each month.
This is where looking beyond the headline affordability figures matters.
Could Buying in Hull Be More Achievable Than You Think?
For someone who has assumed buying a home is still out of reach, these figures may be a useful reason to look at their position again.
Being named among Britain’s most affordable places does not guarantee that you will qualify for the mortgage you need.
It does mean Hull remains comparatively accessible when property prices are measured against local earnings.
Our mortgage advisors in Hull can look at your income, deposit and existing commitments to establish how much you may be able to borrow before you start viewing properties.
We can then compare suitable mortgage products from a wide range of lenders, giving you a clearer idea of your budget and what buying a home in Hull could realistically look like.
Date Last Edited: 10/05/2026